
It’s been a mad March on the mortgage front, that much is for sure. And if your fixed rate is ending in the next few months, this is exactly the moment to pay attention — not panic, but be proactive.
Only a short while ago, things were looking more positive. Through February, rates were gradually easing, the Bank of England seemed confident inflation was heading back towards 2%, and plenty of people were expecting another base rate cut at the next MPC meeting on 19th March.
Then the headlines changed — fast. With conflict escalating in the Middle East (a key region for global oil and gas), markets immediately started worrying about energy prices rising again. And when energy costs rise, inflation can follow. We’re already seeing some of that pressure showing up at the pumps.
That shift in inflation expectations has fed straight into mortgage pricing. Over the past week or so, we’ve seen lenders — big and small — start reversing recent rate cuts. Nationwide, Virgin Money, Halifax and NatWest have all increased selected fixed rates recently, largely because swap rates (which fixed-rate mortgages are priced from) have moved up.
Some lenders have even pulled products temporarily while they wait for more clarity. That tells you everything about the mood: cautious, jumpy, and moving quickly.
So if you’re coming off a fixed rate in 2026, the landscape is suddenly less friendly than many people expected a couple of weeks ago. UK Finance says around 1.8 million fixed-rate deals end this year — and my advice to those households is simple: don’t assume this is a short-lived blip and that rates will automatically drift back down again. They might… but there are no guarantees.
If you’re looking at a mortgage now, or you’re close to remortgaging, the best thing you can do is take action early.
A lot of borrowers don’t realise you can often secure a rate months in advance — and if your lender brings out a better deal later, you may be able to switch onto the cheaper rate before you complete. This is where having a broker in your corner really matters, because we keep monitoring the market and your lender’s pricing so you’re not left behind if something improves.
In terms of choosing a fixed rate:
- If your budget is tight and you value certainty, a longer fix (like 5 years) can be a sensible way to protect yourself against volatility.
- If you’ve got more breathing space and you’re comfortable with a bit of risk, a shorter fix might be worth considering.
There’s no one-size-fits-all — it comes down to your circumstances, your goals, and how much payment movement you could realistically tolerate.
But overall, this isn’t a time for guesswork. Inflation, swap rates and global events are all moving quickly — and the borrowers who do best are the ones who move early too. Know your numbers, make a deliberate choice between flexibility and payment security, and don’t leave it until the last minute when your options may be more limited.
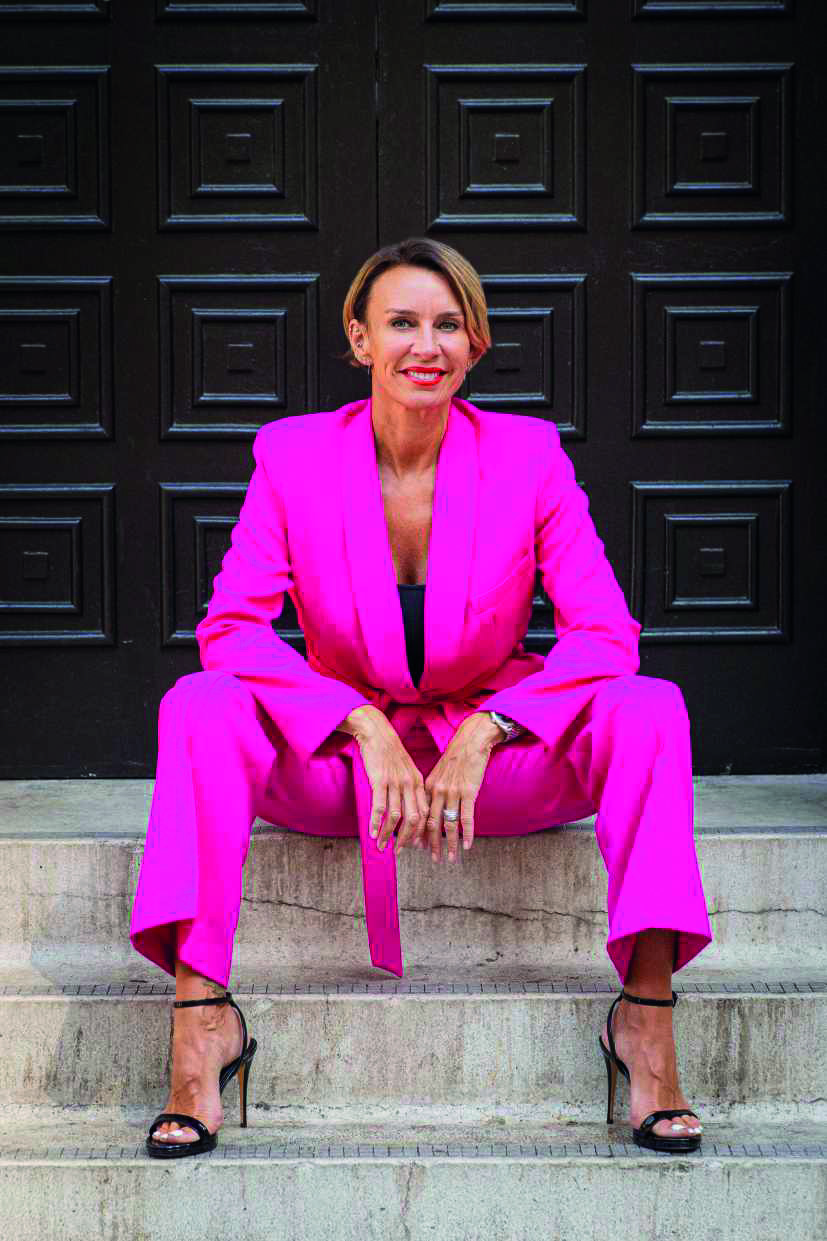 Katy Eatenton
Katy is a mortgage and protection specialist at Lifetime Wealth Management with over 20 years experience in the industry. She has won several awards for her customer-centric approach and expertise and is regularly featured in the trade press, where she provides insights on the market and tips on best practice.
Katy’s contact details:
Tel: 01932 216045. Email: weybridge@lifetime.co.uk
Instagram: Katyeatenton_finance.strategy
You can even book directly in Katy’s diary at: www.calendly.com/katyeatenton_finance
Katy has a regular column in Premier Magazine