
At the beginning of the year, the mortgage market finally appeared to be moving in the right direction. Inflation was easing, interest-rate cuts looked increasingly likely and lenders were competing more aggressively.
But that optimism has since been replaced by considerable uncertainty.
Conflict in the Middle East has pushed energy prices higher and revived concerns about inflation, while volatility in government bond markets has increased the cost of borrowing across the economy. Mortgage rates are consequently moving upwards again.
It is important to understand that fixed mortgage rates are not determined solely by the Bank of England’s base rate. They are heavily influenced by swap rates, that reflect where financial markets expect interest rates to be over the coming years.
If investors believe inflation will remain elevated and the Bank may need to keep rates higher, swap rates can rise before the Bank has made any decision.
That pressure feeds directly into mortgage pricing. Lenders can withdraw a product or announce an increase with very little notice, meaning a deal available in the morning may have disappeared by the following day.
This is particularly important for borrowers with larger mortgages, where even a relatively small rate movement can make a substantial difference to monthly repayments and the total interest charged.
Markets could settle and mortgage pricing could improve, but borrowers should not base an important financial decision on the hope that rates will fall.
My advice is not to panic, but to prepare early. If your mortgage deal ends within the next six months, or you are planning to buy, review your position now. Locking in a rate in advance can provide protection against further increases.
Depending on the lender and circumstances, there may still be an opportunity to move to a better product if rates subsequently fall before completion.
Preparation also means having your documents ready and understanding your wider financial position. This is especially important for borrowers with complex income, bonuses, investments, several properties or plans to restructure their borrowing.
The lowest headline rate is not automatically the most suitable deal when fees, flexibility, early repayment charges and lending criteria are considered.
The outlook for the remainder of the year remains difficult to predict. Much will depend on how the Middle East crisis develops, energy prices, inflation and how the Bank of England responds.
Markets could settle and mortgage pricing could improve, but borrowers should not base an important financial decision on the hope that rates will fall.
The lesson from this year is how quickly expectations can change. You cannot control financial markets, but you can make sure you understand your options, act early and avoid being forced into a rushed decision after the deal you wanted has disappeared.
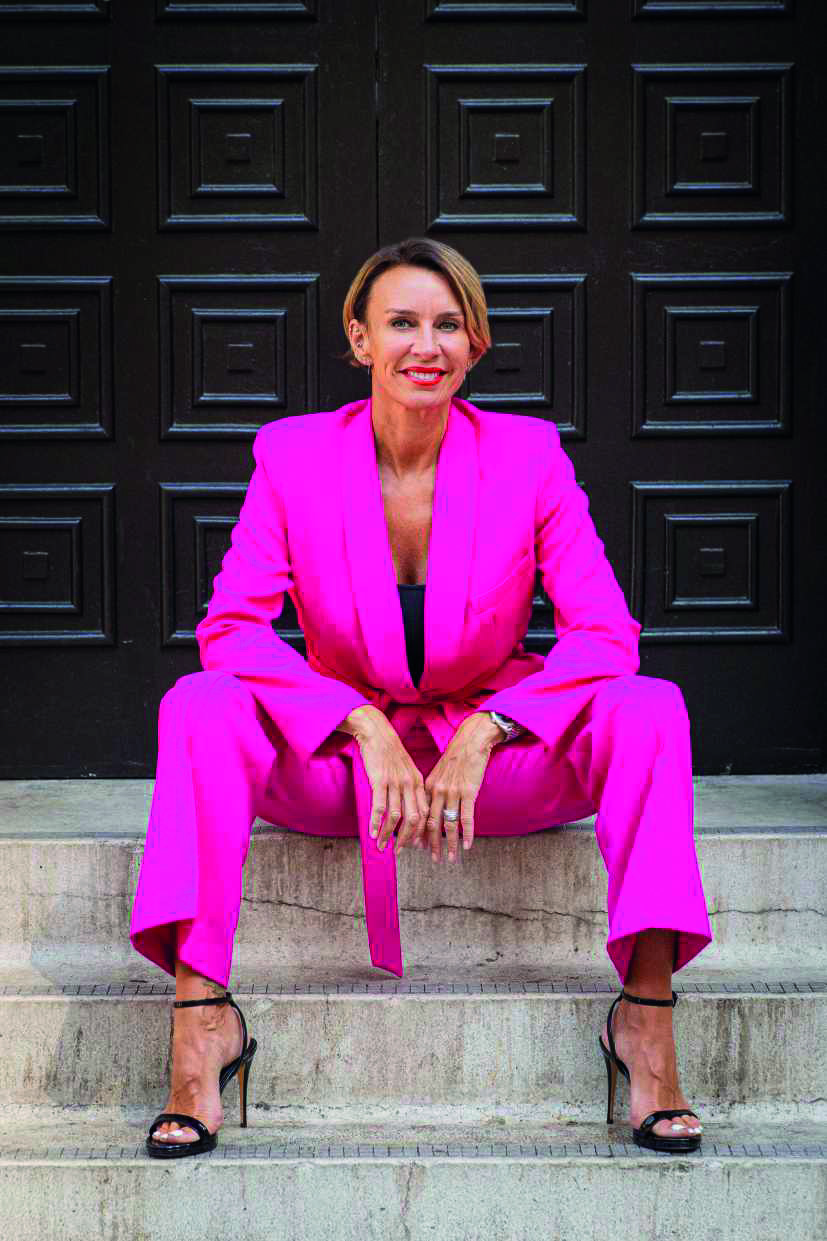
Katy Eatenton
Katy is a mortgage and protection specialist at Lifetime Wealth Management with over 20 years experience in the industry. She has won several awards for her customer-centric approach and expertise and is regularly featured in the trade press, where she provides insights on the market and tips on best practice.
Katy can be contacted on 01932 216045 or weybridge@lifetime.co.uk
On Instagram: Katyeatenton_finance.strategy
You can even book directly in Katy’s diary at: www.calendly.com/katyeatenton_finance
This article also appears in the autumn edition of Premier Magazine